 By
Why Is Robinhood Defending Stock Tokens?
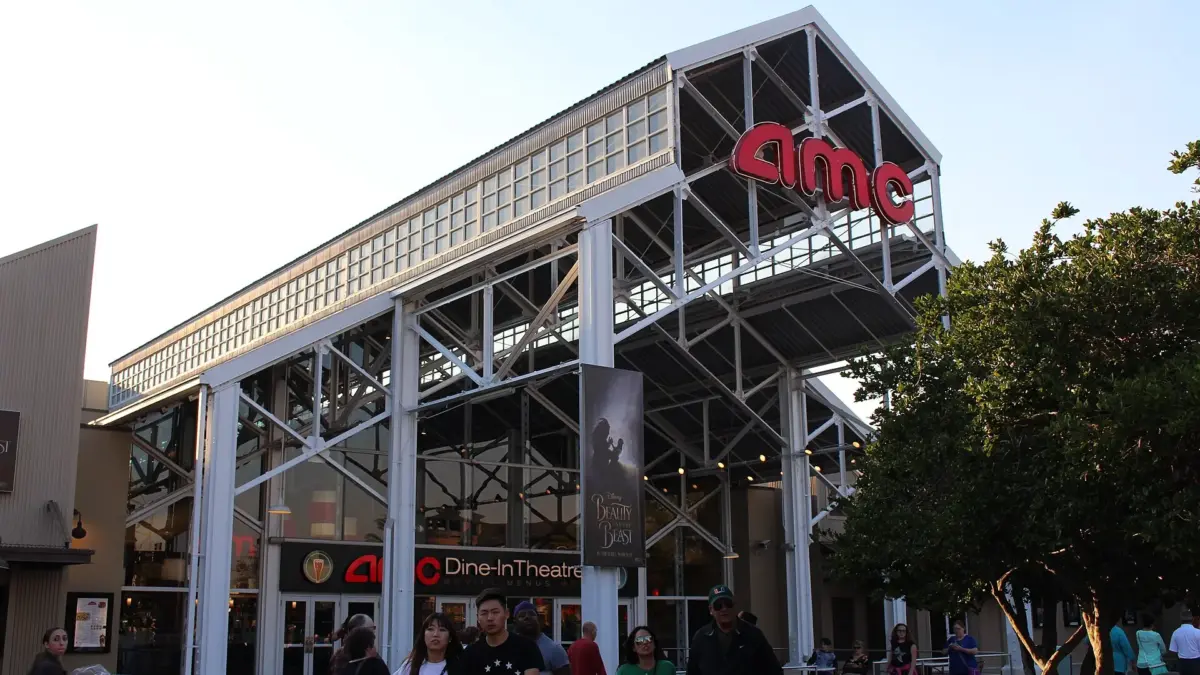
Robinhood CEO Vlad Tenev has stepped up his defense of tokenized stocks, arguing that public companies should not be able to prevent third parties from creating blockchain-based products tied to freely traded shares. The comments extend a dispute with AMC Entertainment CEO Adam Aron, who has demanded that Robinhood stop offering tokens linked to AMC shares and threatened to raise the issue with the U.S. Securities and Exchange Commission. Tenev said the central regulatory question is not whether a product uses blockchain technology, but whether it changes the legal rights attached to the underlying security. “A company should control the rights attached to its shares — not every lawful use of those shares once they’re in investors’ hands,” Tenev wrote on X. “Going onchain shouldn’t give the issuer a veto it never had offchain.” Robinhood launched stock tokens outside the U.S. in June 2025, providing exposure to hundreds of U.S. stocks and exchange-traded funds. The products are separate financial instruments backed 1:1 by underlying shares, according to Tenev, rather than direct entries on the issuer’s shareholder register. That distinction matters because token holders receive economic exposure to a stock without necessarily receiving the same legal status, governance rights or shareholder relationship as direct owners of the underlying shares.Where Do Robinhood and AMC Disagree?
AMC’s objection focuses on the creation of a parallel product linked to its shares without the company’s approval. Aron has described Robinhood’s product as a “fictitious synthetic equity market” and argued that such instruments could confuse investors, weaken AMC’s ability to raise capital and create a market using the company’s name without issuer consent. Tenev rejects the idea that issuers should control every financial product referencing their stock. He compared tokenized stock exposure with established instruments such as options, unsponsored American depositary receipts and structured products, which can reference publicly traded shares without giving the underlying company control over their creation. “If it creates a separate financial instrument that holds or references freely transferable shares without changing the issuer’s rights, obligations, or authoritative shareholder record, issuer consent should not be required,” Tenev wrote. He drew a clearer boundary around products that would change the underlying security itself. If tokenization alters shareholder rights, replaces the company’s official stock ledger or creates new obligations for the company or its transfer agent, Tenev said the issuer should be involved.Investor Takeaway
The dispute is less about blockchain technology than about where legal ownership ends and financial replication begins. If regulators treat stock tokens like other third-party derivatives, issuers may have limited control over their creation. If the products are viewed as substitutes for shares, companies could gain a stronger role.
